Hour-long cheap petrol waits as housing cost pressures heat up
SA motorists are lining up for hours to cash-in on petrol discounts as local property leaders raise interest rate hike concerns. See the video.
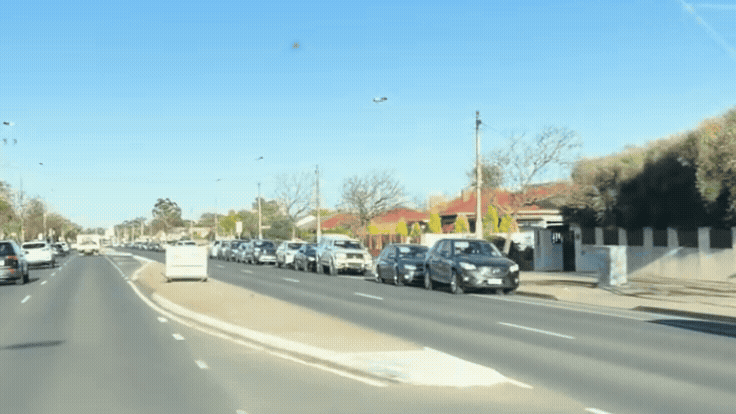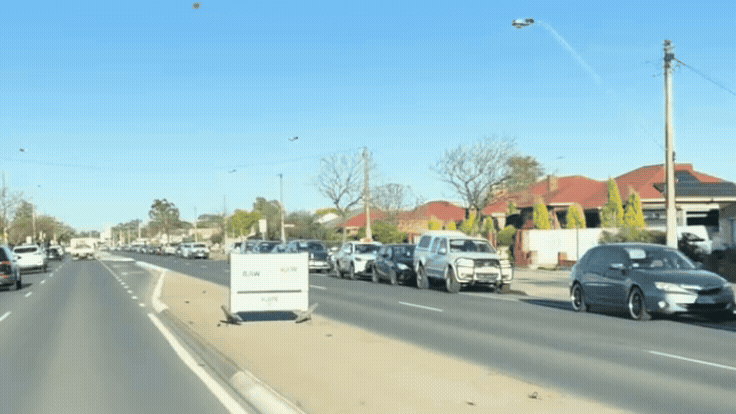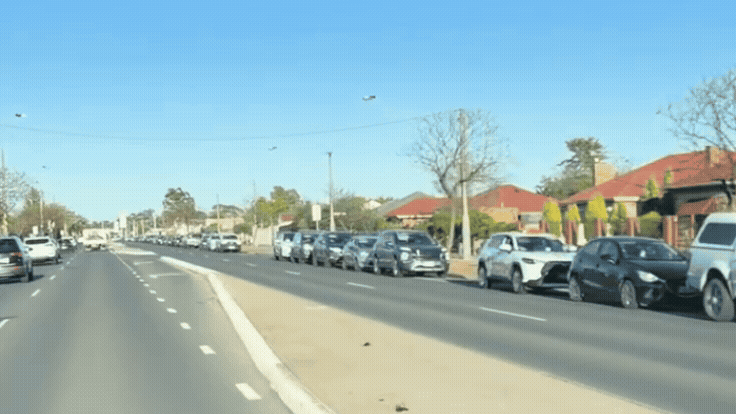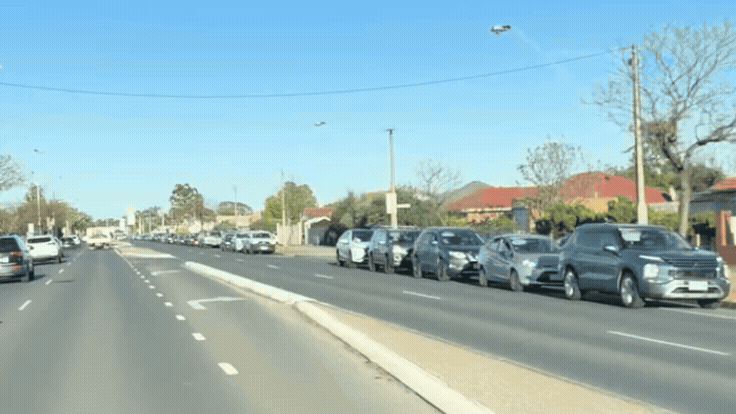
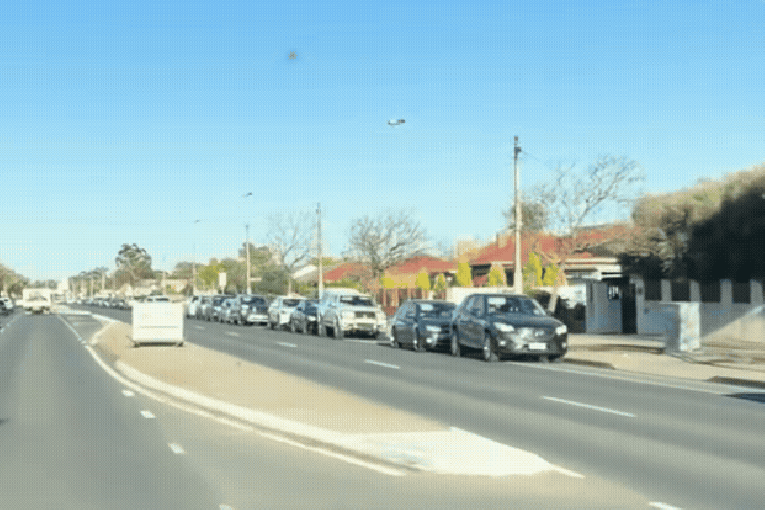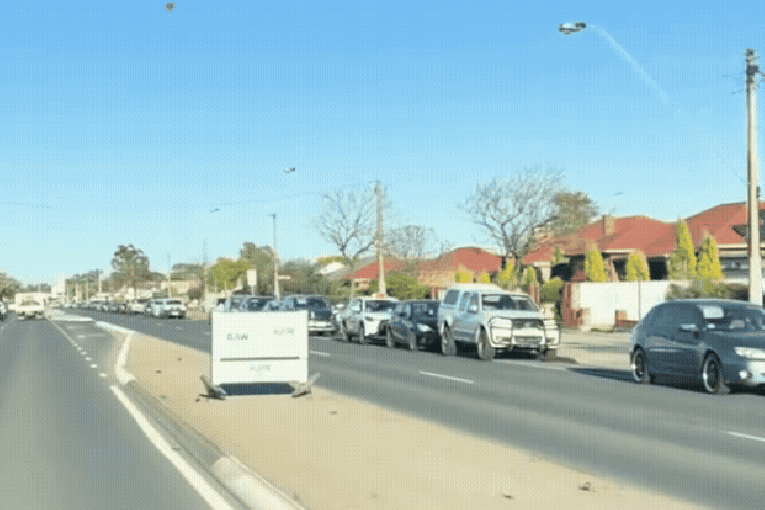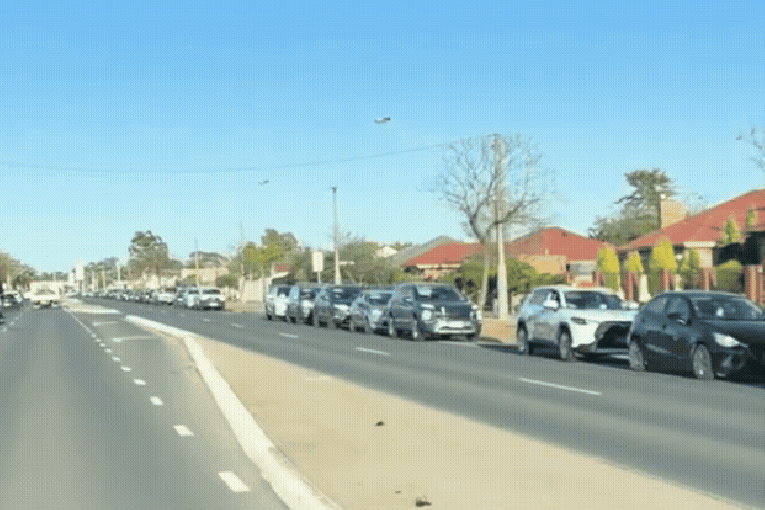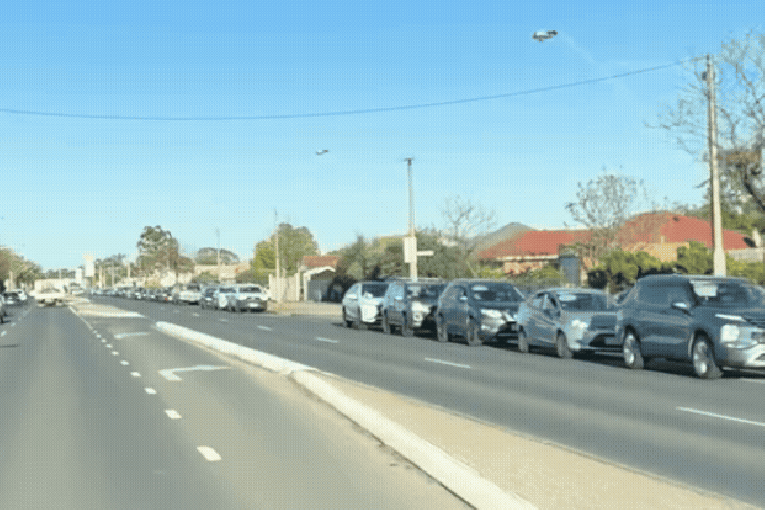
Cash-strapped Adelaide motorists have been seen lining up for hours along Daws Road in Edwardstown for petrol discounts as cost-of-living pressures continue to ramp up.
It comes as Australian mortgage holders have been slugged with a fifth interest rate hike for the year.
Melbourne billionaire Adrian Portelli and owner of LMCT+, a subscription-based trade promotion and loyalty rewards club in Australia, opened a member’s only petrol station in Edwardstown in October, offering petrol at discounted prices.
A video taken by InDaily one Saturday in October shows hundreds of motorists queuing from the petrol station on the corner of Daws and South Road for more than one-kilometre down the road. Some motorists reportedly waited in line for more than one hour, according to social media reports.
As of Wednesday, the petrol station is offering unleaded petrol at $212.9, compared to petrol stations closer to the CBD at $229.9 a litre.
You might like

Adelaide economist Dr Susan Stone said “saving even the smallest amount can translate into a lot every week” through petrol savings.
“For tradies, Uber drivers or other delivery services or just anybody whose job requires them to be driving around all the time it’s a relatively large share of their budget, so it makes sense for them to want to save for that,” Stone said.
“The problem becomes when your income doesn’t go up, and especially when certain goods that you buy a lot of increase in costs.
“We need less spending on discretionary items, and for people to put off that renovation or put off that new car purchase. If they can put that off it can give the economy a bit of breathing room.”
The Reserve Bank of Australia (RBA) has delivered a fifth interest rate hike for 2026, adding more pain for variable-rate borrowers.
The hike will see the average owner-occupier with $600,000 remaining on their mortgage forced to find an extra $100 a month.
Stay informed, daily
Since February, that same borrower now needs to find a cumulative $500 per month in order to meet their repayments.
In its monetary statement, the RBA board said it was necessary to clamp down on inflation before it became an expected part of the economy.
“Capacity pressures appear a little tighter than previously estimated and there are indications that higher fuel prices are being passed through to prices of other goods and services,” the board said in its statement.
Belle Property senior principal Calvin Lai told InDaily that rising interest rates and recent changes to capital gains taxes had raised the alarm for many SA homeowners.
“At the moment now, we haven’t seen that people are being forced to sell their properties, but if the interest rates keep rising, then of course you will raise the alarm,” Lai said.
“In Adelaide it is not as bad compared to Sydney and Melbourne, but there’s a lot of people concerned about interest rates rising, and obviously they affect the people who rely on their wage to service their mortgage.”
Recent data from property research group Cotality showed that almost every suburb across Brisbane, Perth and Adelaide has recorded a drop in values over the past three months as buyers struggle to get loans because of higher interest rates.
The latest Cotality Home Value Index for October, released on Monday, shows another 1.2 per cent drop in the national median to $884,855.
Lai said property investors had seen the greatest impact of recent capital gains tax changes, with some investment properties being sold for less than purchase price, raising concerns for the future of the housing economy.
“If the housing economy is affected, then you’re gonna affect lots of industries across the board, from tradesmen, builders, and real estate businesses,” he said.
“I think the Australian government needs to look at other developed countries, and why Australia needs to be so aggressive with interest rates compared to these countries.”
Want to see more stories from InDaily SA in your Google search results?
- Click here to set InDaily SA as a preferred source.
- Tick the box next to "InDaily SA". That's it.